Ask ten people what “retire early” costs and most will throw out one intimidating number: ₹5 crore. Maybe ₹10. It sounds so far away that they close the tab and go back to their EMIs. But that single scary figure is the biggest myth in the whole FIRE conversation.
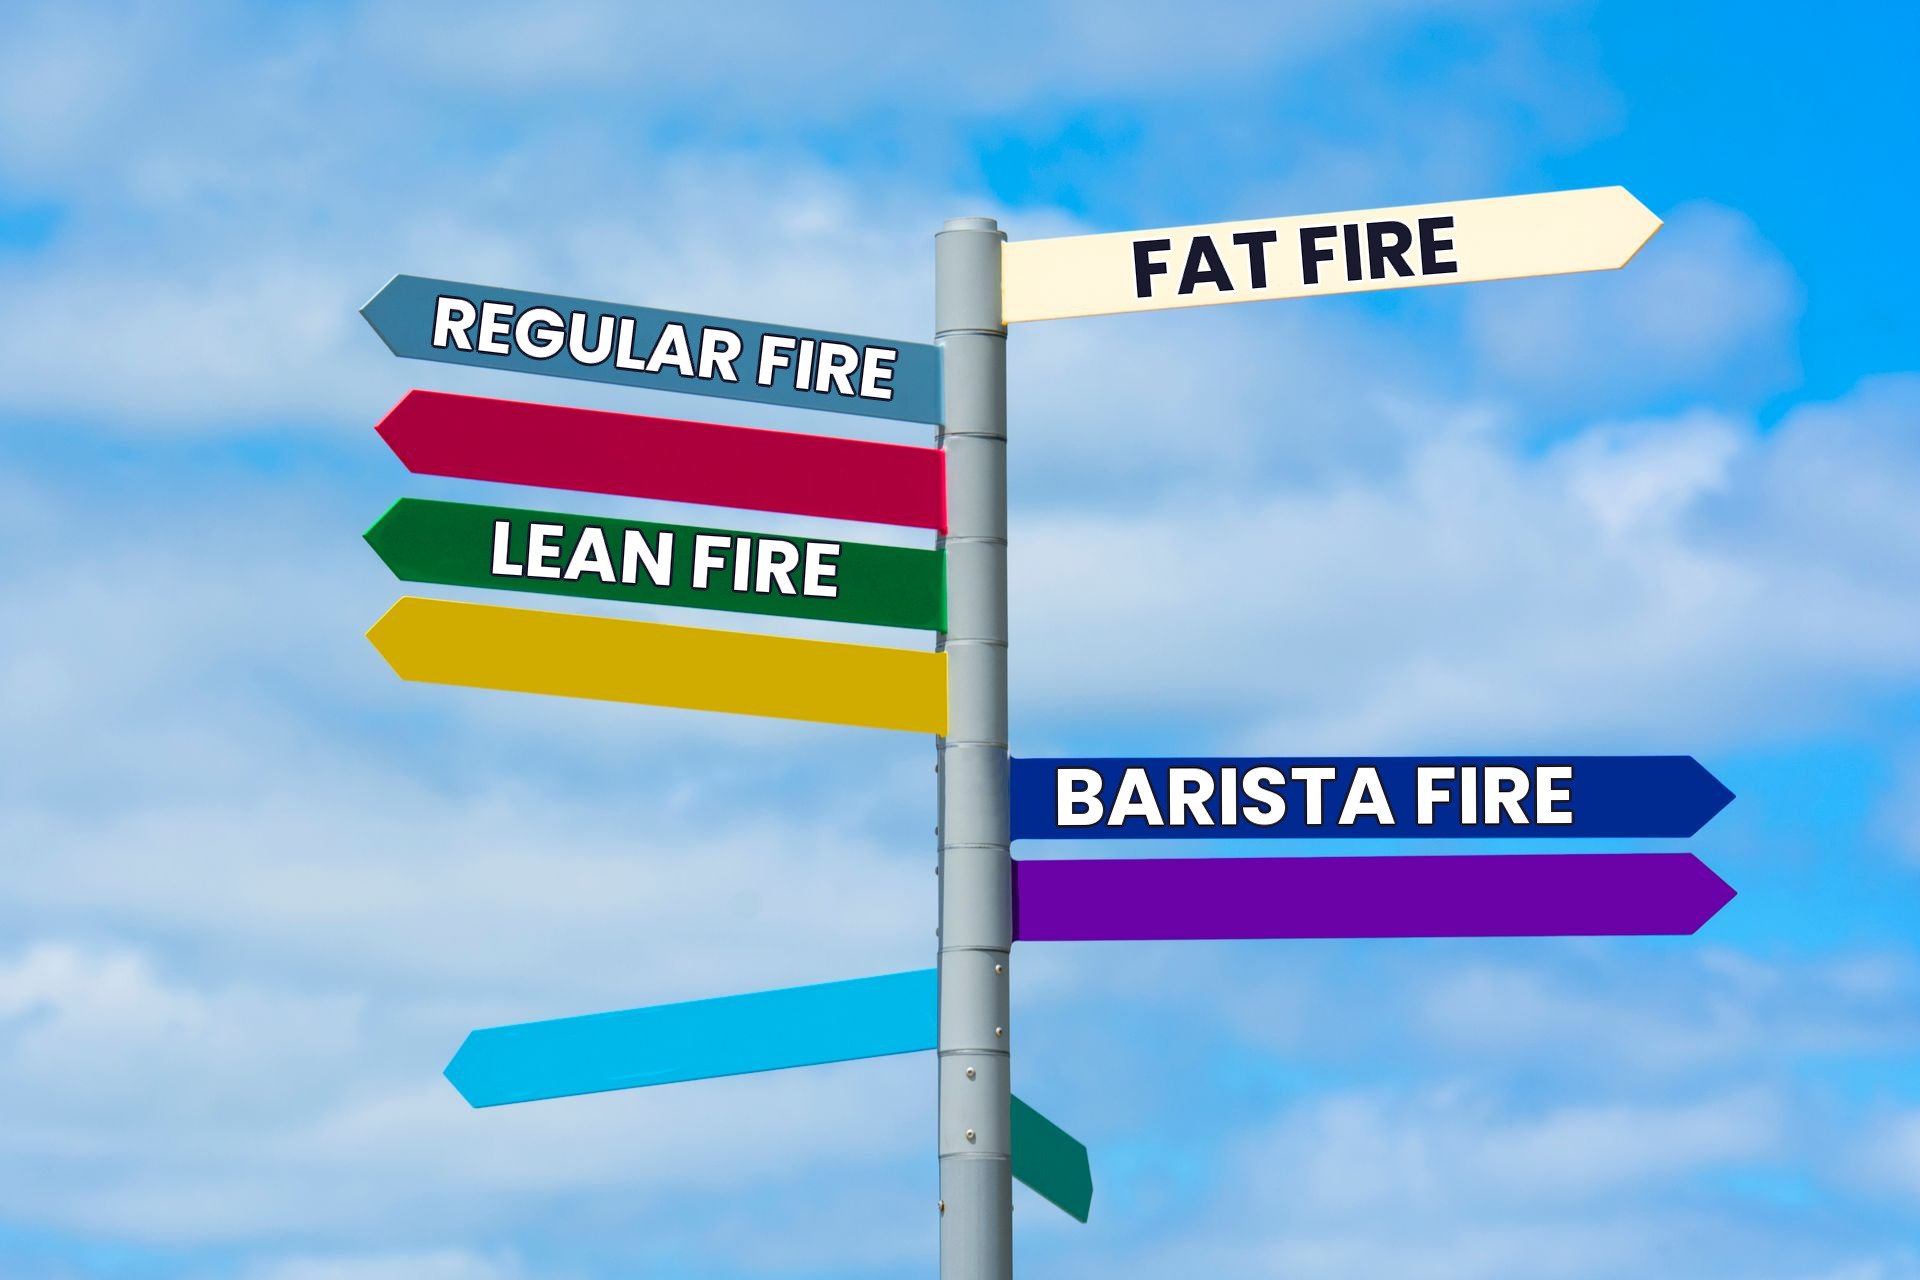
Here’s the reframe that changes everything. FIRE isn’t one finish line — it’s a menu. The frugal 30-year-old in Indore who’s happy on ₹40,000 a month and the Bangalore couple spending ₹1.8 lakh a month are chasing wildly different targets, and both are valid. The trick is knowing which version fits your life before you exhaust yourself sprinting toward someone else’s number.
So let’s break down the four main types of FIRE in India — Regular, Lean, Fat, and Barista — with realistic rupee figures for each, and a simple way to pick yours.
Why FIRE isn’t one number
Every type of FIRE runs on the exact same engine: the 4% rule. Save roughly 25 times your annual expenses, and you can withdraw about 4% a year without draining the corpus. That maths never changes.
What changes is one input — your annual expenses. And that single number is entirely personal. A family living on ₹6 lakh a year needs a ₹1.5 crore corpus. A family living on ₹20 lakh a year needs ₹5 crore. Same rule, same 25x, totally different destination.
That’s the whole idea behind the different “types.” They aren’t different formulas — they’re different lifestyles, each with its own price tag. Once you see it that way, FIRE stops being one impossible mountain and becomes a target you get to define. So the real question isn’t “how do I reach ₹5 crore?” It’s “which version of freedom am I actually building toward?”
Regular FIRE — the comfortable baseline
Regular FIRE is the middle of the menu, and it’s the one most salaried Indians actually mean when they picture retiring early. You keep a comfortable urban lifestyle — good food, an annual holiday, school fees covered, a decent car — you just fund it from your portfolio instead of a paycheck.
Think monthly expenses in the ₹75,000 to ₹1.5 lakh range. That puts your FIRE number somewhere between ₹2.7 crore and ₹5.4 crore. It’s an ambitious target, but genuinely achievable for a dual-income household with a healthy savings rate over 15 to 20 years.
Treat Regular FIRE as your anchor. Lean is simply a lighter version of this, and Fat is a heavier one. Everything else on the menu is measured against this baseline.
Lean FIRE — freedom on a frugal budget
Lean FIRE is for people who are genuinely happy living simply. You keep expenses low — usually under ₹40,000 to ₹50,000 a month — which shrinks the corpus you need and gets you to freedom years faster than everyone else.
The target here lands around ₹1.5 crore to ₹2 crore. That often means a Tier 2 or Tier 3 city, minimal discretionary spending, and a deliberate, no-frills lifestyle. For the right person, it’s liberating. You’re buying back your time at the lowest possible price.
But Lean FIRE in India carries a real risk that the frugality glamour usually skips over.
A ₹1.5 crore corpus leaves almost no cushion for India’s two big shocks — medical inflation running at 12–14% a year, and no state safety net. One serious hospitalisation or an ageing parent’s care can crack a lean plan wide open. If you go Lean, budget separately for health insurance and an emergency buffer on top of your FIRE number.
Fat FIRE — early retirement without cutting back
Fat FIRE flips the philosophy. Instead of shrinking your life to fit a smaller corpus, you build a bigger corpus so you never have to shrink your life at all. Premium housing, business-class travel, top schools, eating out whenever you like — all of it stays, funded entirely by your investments.
Naturally, that comfort has a price. With monthly expenses of ₹1.5 lakh and up, your FIRE number starts at ₹5.4 crore and climbs from there. Reaching it usually demands a high income, a strong savings rate, and patience. It’s common among senior executives, founders, and business owners who’d rather work a few extra years than compromise on lifestyle later.
Fat FIRE isn’t greedy — it’s honest. If you know you won’t be happy pinching every rupee in “retirement,” better to build for the life you actually want than to reach freedom and quietly resent it.
Barista FIRE — the middle path
Barista FIRE is the most flexible option on the menu, and arguably the most realistic for how Indians relate to work. The idea: you don’t wait until your corpus covers 100% of your expenses. You build enough that compounding handles most of the load, then take a low-stress, part-time, or passion job to cover the rest.
Say your corpus throws off ₹40,000 a month and your life costs ₹70,000. You just need light work — consulting, teaching, freelancing, a small venture — to bridge that ₹30,000 gap. No more corporate grind, no more Sunday dread, but you’re not fully drawing down your portfolio either. Because of that, your corpus target can be meaningfully smaller than Regular FIRE.
Many Indians find this the sweet spot precisely because our culture rarely wants to stop working entirely — we just want to work on our terms. For a real-world walk-through of the numbers, see our BaristaFIRE in India story.
The four types at a glance
Here’s how the whole menu compares side by side, using realistic Indian figures:
| Type | Monthly spend | Corpus needed | Best for |
|---|---|---|---|
| Lean FIRE | Under ₹40–50k | ₹1.5–2 crore | Committed minimalists who value time over things |
| Regular FIRE | ₹75k–1.5 lakh | ₹2.7–5.4 crore | Comfortable urban families, the classic target |
| Fat FIRE | ₹1.5 lakh+ | ₹5.4 crore+ | High earners who won’t compromise on lifestyle |
| Barista FIRE | Any, partly covered by work | Smaller partial corpus + part-time income | Those who want out of the grind but not out of work |
So which type is right for you?
You don’t need a spreadsheet to figure this out — just honest answers to four questions.
1. What do you actually spend?
Not your aspirational budget, your real one. Track three months of expenses. That number, multiplied by 12 and then by 25, is your Regular FIRE target. Everything else flexes around it.
2. How much do you enjoy your work?
If the thought of never working again fills you with relief, lean toward Lean or Regular. If you actually like what you do but hate the pressure and politics, Barista FIRE may fit better — you get freedom without giving up the part you enjoy.
3. How high is your income runway?
Fat FIRE only works if you can genuinely save at a high rate for years. If your income is solid but not spectacular, Regular or Barista will get you there far sooner than chasing a ₹5 crore-plus corpus you can’t realistically fund.
4. How much risk can you stomach?
Lean FIRE has the thinnest margin for error, so it demands discipline and strong insurance. If uncertainty keeps you up at night, aim a little higher — a slightly bigger corpus buys a lot of peace of mind. Before you lock in any target, stress-test it: run your number through the SWR Calculator to see what it would safely pay you each year over a 30-to-40-year retirement.
Whichever type you land on, the path to it is the same discipline covered in our Complete Guide to FIRE in India — a high savings rate, sensible investing, and time in the market. The type just tells you where the finish line is.
Frequently Asked Questions
Not sure which number is yours?
Plug in your real expenses and see the corpus each type of FIRE needs for your life.
Written by Team Let's Get FIREd
Let's Get FIREd is an independent, India-first resource on Financial Independence and Retiring Early. We turn the maths of FIRE into plain, rupee-first guides, calculators and real stories for salaried Indians. Everything here is researched for Indian markets, inflation and tax rules — and is for education only, not personalised financial advice. More about us → · Our editorial standards →